Every enrollment form is a negotiation. You want a name, an email, a phone number. The customer wants to be done. The usual compromise is a form that is short enough to finish and long enough to be wrong: typos in the email, a phone number with a digit missing, a name entered as "asdf" because the field was required and the customer was in a hurry.
In the Nordics, there is a better answer sitting on almost every phone. Vipps, and MobilePay in Denmark, Finland and Sweden, is how people already pay each other, and it doubles as a login. Stell is a Vipps partner, and Vipps Login is built into our enrollment flow: a customer joining your program can skip the form entirely and sign in with Vipps instead.
How it works for the customer
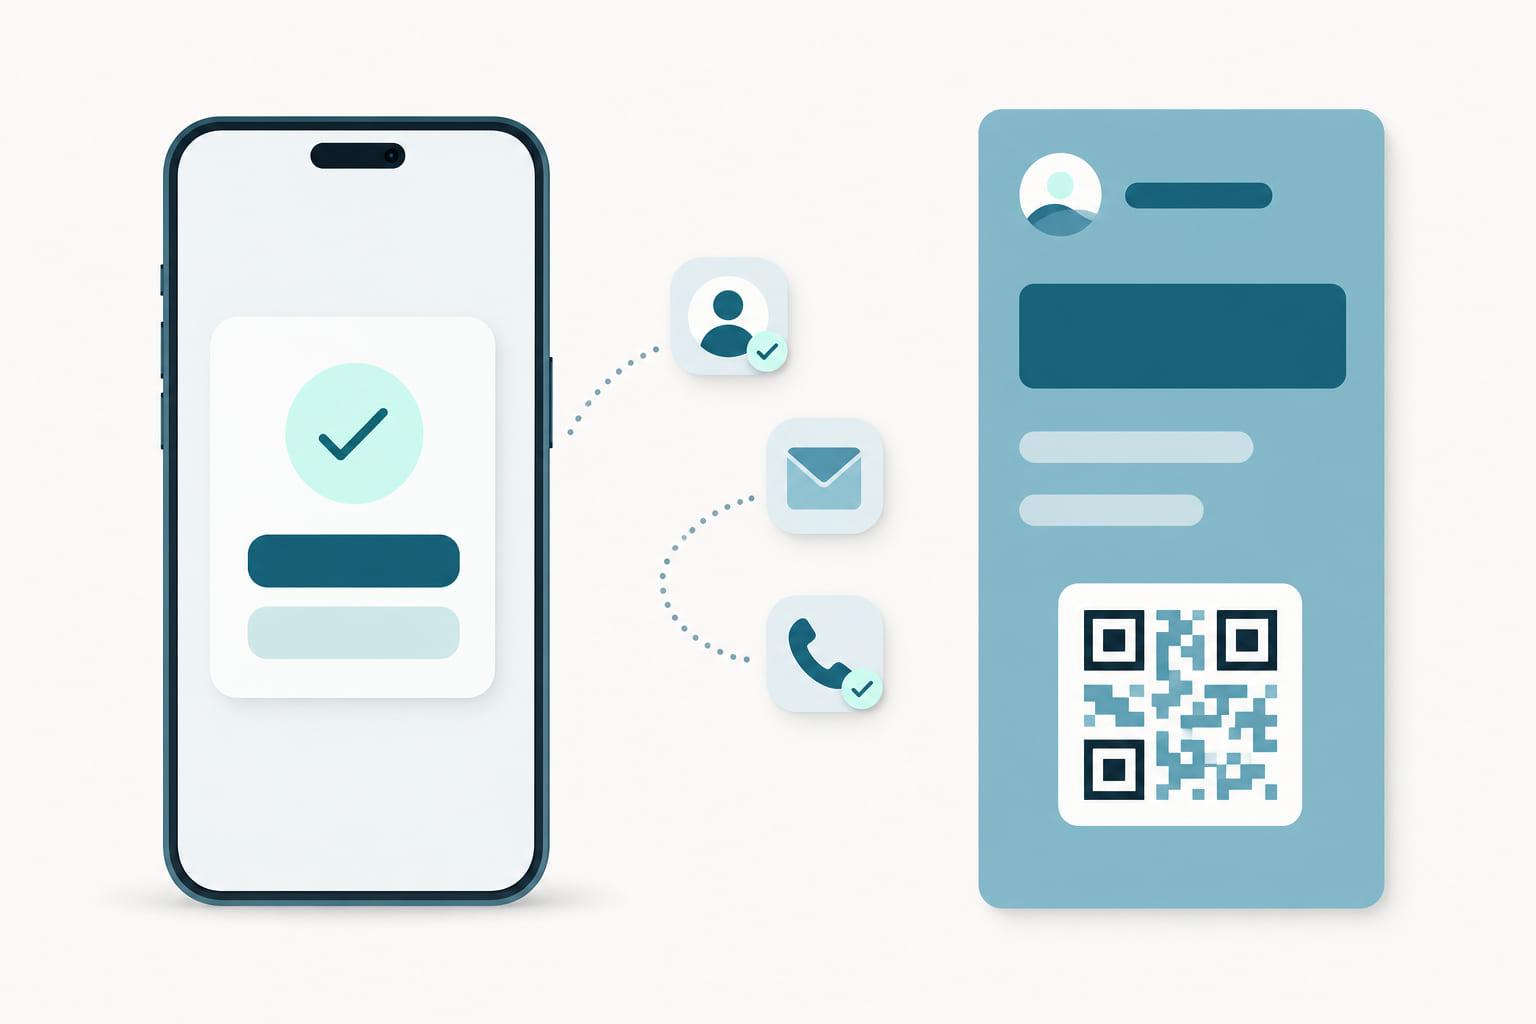
The customer opens your join page, taps "continue with Vipps", and approves in the Vipps app they already have. The app shows exactly what will be shared, they confirm, and they are back in the flow with everything filled in. From there it is one step to the finish: the pass lands in their wallet, live and connected to your program.
That is the whole flow. No account to create, no password to invent, no email verification loop waiting in an inbox. The customer proves who they are with two taps in an app they use every week, and the reward is immediate and visible: a pass on their phone.
How it works for your data
This is where Vipps Login earns its place, because the data it returns is not what the customer typed. It is what Vipps has verified.
Every Vipps user is KYC-verified: their identity was confirmed when they signed up, the same way a bank confirms it. When a customer enrolls through Vipps Login, your program receives the details you have chosen to collect, typically their real name, a verified phone number and a verified email address, exactly as they exist in a system with a strong incentive to keep them correct.
Compare that to a form. Form data is self-reported at a moment when the customer's goal is to get past the form. It decays from the first keystroke: the throwaway email, the old phone number, the nickname in the name field. Every downstream use, from receipts to campaigns to support lookups, inherits those errors.
Verified enrollment changes what a new member is worth. A record you can trust on day one is a record you can act on: campaigns reach a real inbox, SMS reaches a real phone, and the customer at the till matches the customer in your CRM. And because Stell syncs enrollment data with your CRM, that clean record arrives in your system of record ready for the same segmentation and automation as the rest of your base, with no de-duplication project waiting down the line.
Consent, handled properly
Identity is only half of what enrollment collects; the other half is permission. The consent screen in the join flow shows the customer exactly which details they are sharing, and marketing consent is captured explicitly as its own choice, not buried in a checkbox they scrolled past. What you get is not just better data but better-founded data: contact details you can actually use, attached to a consent the customer visibly gave.
That matters more every year. A list built from verified identities and explicit consent is an asset; a list built from hurried form fills is a liability with open rates.
Where this fits in your enrollment mix
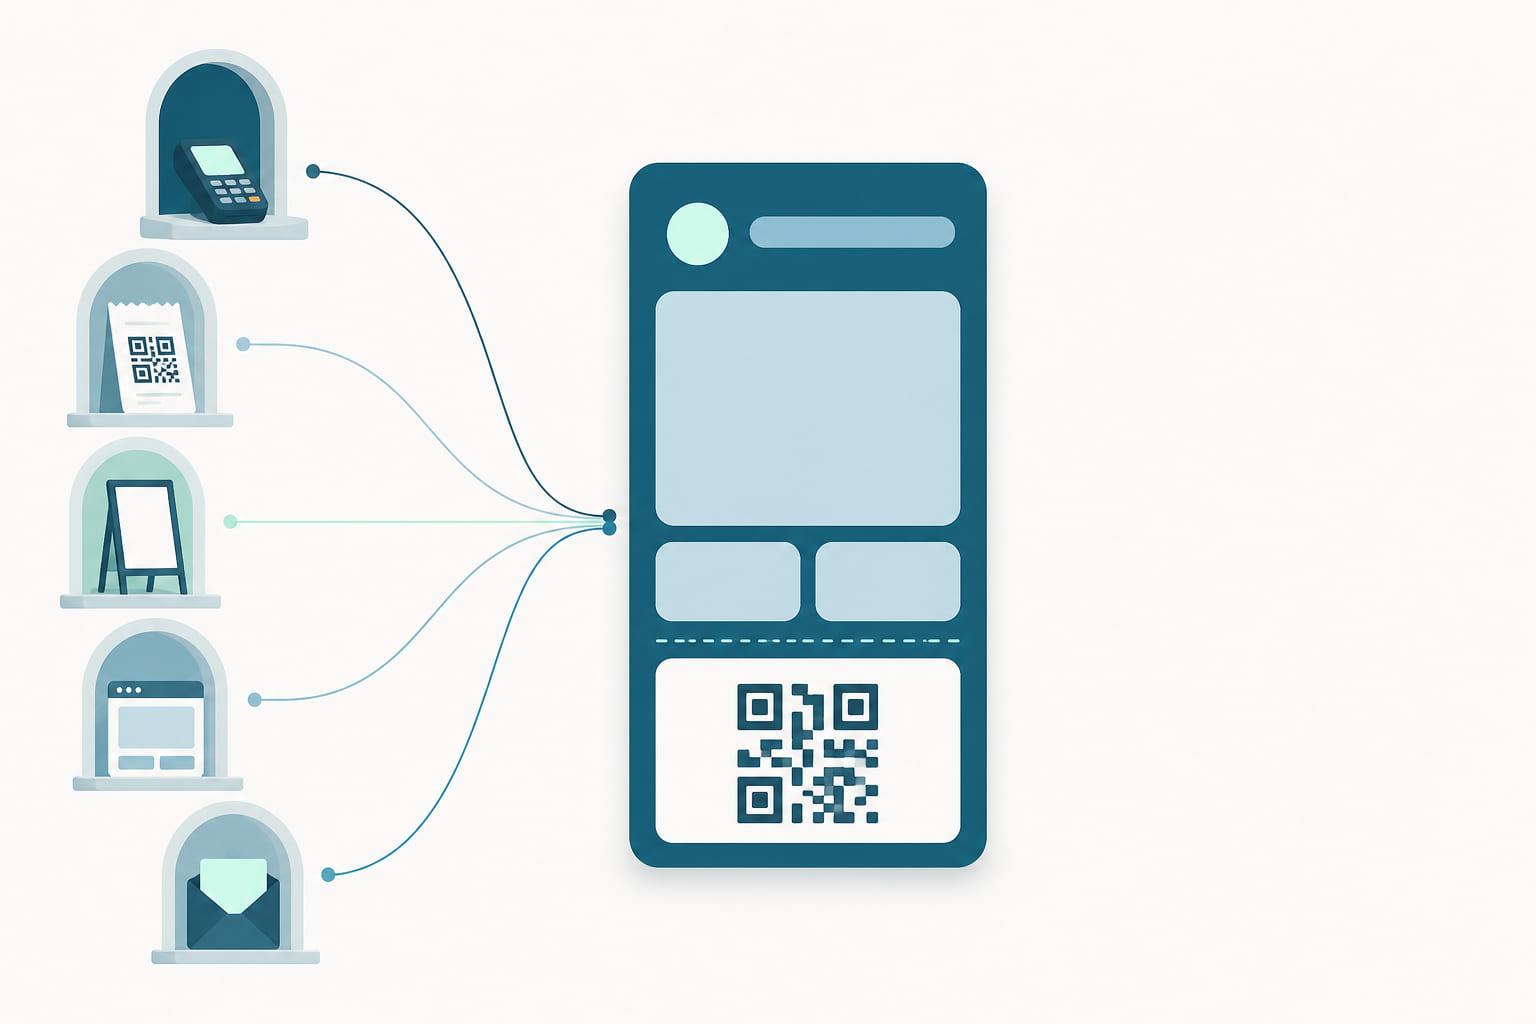
Vipps Login is not a separate channel so much as an upgrade to all of them. Wherever your join flow runs, a QR code on the counter, a link in a campaign, a prompt after online checkout, the Vipps option replaces the form step with two taps. That holds across every place a customer can join, including the moment right after payment where most programs lose members to a form. The flow stays the same; the friction and the typos leave.
This is not theory. Norwegian retailers run their customer clubs on it today: Megaflis enrolls Megaflis+ members through Vipps Login, and Extra Leker does the same for its Extra Leker Venn club. In both cases the customer signs in with Vipps, the verified details flow into the program, and the membership pass lands in the wallet in the same motion.
It pairs especially well with in-store enrollment, where the case for speed is strongest. A customer scanning a counter QR code between paying and leaving will not type their address into a phone form, but they will approve a Vipps prompt. The moments where forms fail hardest are exactly the moments where a one-tap identity works best.
For merchants in the Nordics, the groundwork is already laid: the app is already on your customers' phones, the trust is already established, and Stell has already done the integration. Enrollment that used to be a form becomes a tap, and every membership starts with data you can build on. If you want to see the flow end to end, from the Vipps prompt to the pass in the wallet, book a demo.